Serica Energy announced on 26 July a recommended cash offer for Pharos Energy, the London-listed producer with assets in Vietnam and Egypt, valuing it at about £145.7m.
Why Serica Energy plc is buying Pharos Energy plc
Serica said the deal would diversify it beyond the UK North Sea. On a pro forma basis its 2P reserves would rise by 13% to 156.8m barrels of oil equivalent and 2C resources by 15%, with expected 2026 exit production of about 70,000 boe a day. Pharos had a debt-free balance sheet with about $45m of cash at 30 June.
“The acquisition of Pharos is a compelling opportunity”
Deal terms and financing
Pharos shareholders were offered 28.6683p in cash plus a 4p special dividend, a 28.6% premium to the undisturbed price on 23 June and 20% above Ratio's original 28p offer. Serica placed the cash in a blocked account and planned to fund it from existing cash and its reserve-based lending facility. Aberforth Partners gave an irrevocable undertaking over about 14.3% of the shares.
Regulatory approvals and timing
The scheme required approvals in Vietnam and Egypt. It fell away after Ratio raised its offer to 32.8183p on 7 August; Serica said on 10 August that its terms were final and confirmed on 13 August that it would not proceed.
Market context
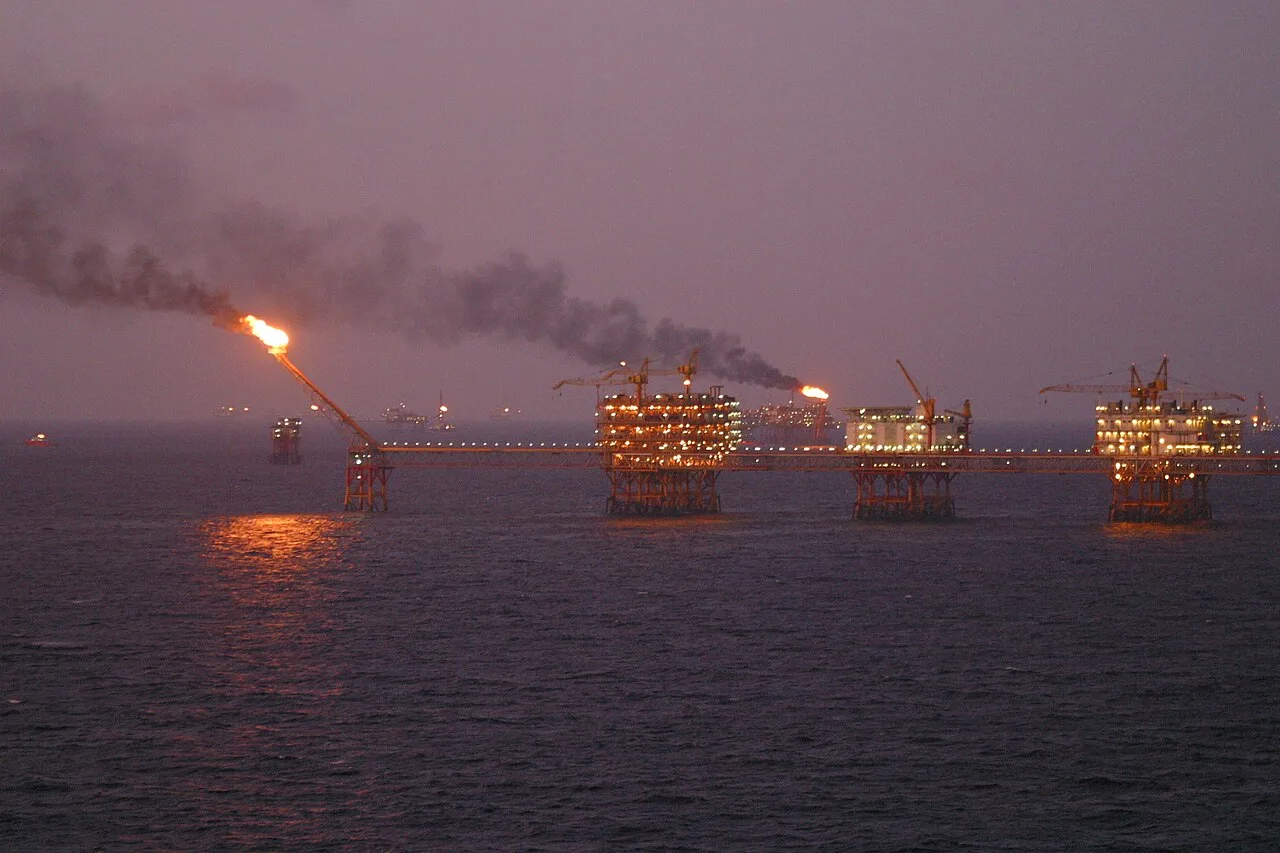
Pharos holds interests in the Te Giac Trang and Ca Ngu Vang fields offshore Vietnam and a 45% interest in the El Fayum and North Beni Suef concessions in Egypt. It produced 5,398 boe a day net in 2025 on revenue of $114.6m.